






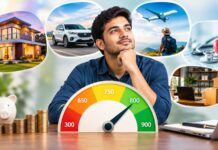


Whether you are struggling to bounce back from a bad credit history or looking to step up from a good score to the elite 800 club, here is why your CIBIL score dictates your life’s biggest milestones—and how to master it
(OdishaPlus Knowledge Series)
In modern India, your financial life is quietly governed by a three-digit number. Whether you are walking into a bank to buy your dream home, financing a vehicle, or trying to get approved for a credit card, lenders look at your CIBIL score before they look at anything else.
Yet, for most of us, this number feels like a mysterious black box. Why do some people find themselves trapped with a bad score despite earning a steady income, while others sitting comfortably above 750 wonder what it takes to reach the elusive 800+ elite tier?
Understanding how this system works is essential for everyone. More importantly, understanding why you need to protect and nurture that score can save you lakhs of rupees and protect your family during critical life moments.
Part 1: Why Does a High CIBIL Score Actually Matter?
Before looking at how to fix or improve a score, it helps to understand what a high CIBIL score buys you. It is not just a digital badge of honor; it is a financial shield and a passport to major life milestones:
Buying a Home (The Mortgage Milestone): A home loan is a 15-to-30-year commitment. A borrower with an elite score (800+) often qualifies for the absolute lowest interest rates available. On a ₹50 lakh home loan, even a fractional difference of 0.25% to 0.5% translates to lakhs of rupees saved in pure interest outgo over the tenure.
Emergency Medical or Personal Financing: Life is unpredictable. In sudden medical emergencies or urgent family crises, having to scramble for an unsecured personal loan can add immense stress. A high CIBIL score ensures instant, pre-approved disbursal within minutes, bypassing lengthy document checks.
Business & Entrepreneurial Dreams: If you plan to start a small business, banks and lenders heavily evaluate your individual CIBIL score as a promoter or director before sanctioning working capital loans—especially when your enterprise is new and lacks a deep financial history.
Global Mobility & Professional Standing: Increasingly, landlords, housing societies, and even certain international background verification processes check credit reliability to assess overall discipline and trustworthiness.
Part 2: Category 1 — Why Bad Scores Happen to Good People (And How to Fix Them)
It is a common heartbreak: you have a steady job, you pay your bills, and yet your CIBIL score drops below 650 or sits in the troubled zone. A bad score is rarely a reflection of your character; rather, it usually stems from a few specific mechanical missteps.
Why Your Score Takes a Hit:
Missed or Delayed EMIs: This is the heaviest penalty. If you miss a credit card payment or loan EMI by even a few days, lenders report it to credit bureaus. Payment history accounts for roughly 30% to 35% of your score.
High Credit Utilization (Maxed-Out Cards): Relying heavily on your credit cards and maxing out your available limit signals financial distress to algorithms, even if you eventually pay the bill.
Guarantor Liability: If you signed as a guarantor for a friend or relative’s loan and they defaulted, that default damages your credit report just as severely as theirs.
Unnoticed Errors: Outdated records where closed loans still show as “Active” or clerical errors in your PAN card can drag your score down without your knowledge.
The Recovery Roadmap:
Clear Dues and Settle Accurately: Prioritize paying off overdue balances. If you settle an account for a lower amount, ensure it is updated correctly, though closing it fully with a “Paid/Closed” status is always preferred.
Automate Repayments: Set up standing instructions for your bank accounts to ensure your EMIs and credit card bills are paid automatically every month before the due date.
Become an Authorized User: If a family member with an immaculate credit history adds you as an authorized user on their long-standing credit card, their positive payment history can help lift your score over time.
Part 3: Category 2 — Sitting Above 750? Here is How to Push Into the 800+ Elite Club
If your score is already above 750, congratulations—you are in the “low-risk” zone. Banks consider you a reliable borrower. However, moving from the high 700s into the 800+ bracket requires moving past basic habits and mastering financial finesse.
The Technical Terms, Simplified:
CIBIL Score: A three-digit summary of your credit history ranging from 300 to 900, compiled by credit bureaus based on your past borrowing and repayment behavior.
Credit Utilization Ratio (CUR): The percentage of your total available credit limit that you are currently using at any given time.
Hard Inquiry: A formal check triggered when you apply for a new loan or credit card, which temporarily dips your score.
Actionable Strategies to Reach 800+:
Master Your Credit Utilization Ratio (Keep it Under 10%): Even if you pay your credit cards in full every month, a high statement balance reported to the bureau can hurt your score. Keep your total spending across all cards below 10% of your total limit, or pay down your balance before the statement generation date.
Never Close Your Oldest Account: Your average account age matters. If your very first credit card has no annual fee, keep it active by putting a small subscription on it. Closing it shrinks your credit history overnight.
Regulate Hard Inquiries: Stop applying for multiple credit cards or personal loans in a short span. Every application triggers a hard inquiry. When pushing for 800+, maintain a strict cooling period of at least 6 months between credit applications.
Audit Your Credit Report: Pull your free annual CIBIL report to check for ghost errors, mismatched PAN details, or delayed payment tags that were cleared long ago.
Summary Blueprint for Every Borrower:
| Credit Status | Real-Life Impact | Immediate Focus Area | Golden Rule |
| Bad Score (< 650) | Higher loan rejection rates & expensive interest terms | Clearing overdue debt & stopping defaults | Never miss a due date. Automation is your best friend. |
| Good Score (750–779) | Smooth approvals & standard market rates | Lowering utilization & protecting account age | Keep CUR under 10% and never close your oldest card. |
| Elite Score (800+) | Maximum savings, pre-approved offers, & lowest interest tiers | Maintaining discipline & zero hard inquiries | Treat credit as a tool, not extra income. |
By understanding how credit algorithms read your financial behavior and recognizing why a high score matters for life’s big milestones, you can take total control of your financial health.
(Disclaimer:This article is for informational and educational purposes only and should not be construed as professional financial, legal, or investment advice. Credit scoring models are complex, proprietary algorithms managed independently by credit bureaus and financial institutions; individual results may vary based on unique financial histories and institutional lending policies. Readers are advised to consult with a certified financial planner or qualified credit advisor before making major borrowing decisions.)